

Tax Treatment Private Coin Sales: UAE Regulations

Nearly one in ten high-value collectible trades faces unexpected reporting hurdles—an eye-opening stat that shows why clarity matters for UAE owners and investors.
This buyer’s guide explains how jurisdictions often treat collectibles—coins and rounds—differently, and why legal‑tender status can change outcomes. It notes IRS-style framing where coins and precious metals appear as collectibles, so holding period and cost basis may shape results.
The focus here is UAE-centered: individuals usually first check personal income exposure, then any transaction duties tied to channels or cross-border activity. This article uses global concepts—capital gains, dealer vs. investor—to build a practical documentation plan while cautioning that local rules can vary.
Readers are urged to keep clear records: purchase receipts, provenance, and sale agreements. For contextual UAE guidance on digital assets and residency points, see this Dubai guide.
Key Takeaways
- Understand how legal‑tender status (bullion coins vs. rounds) can affect outcomes.
- Track cost basis, holding period, and provenance for every item sold.
- UAE individuals typically review personal income exposure first, then transaction obligations.
- Use global frameworks—capital gains, collectibles, dealer vs. investor—for recordkeeping.
- Keep detailed receipts and agreements; consult advisors for high‑value or frequent activity.
- See practical UAE context at Dubai crypto tax guide.
Who This Buyer’s Guide Is For and What “Private Coin Sales” Means in the UAE
Understanding who looks up guidance on personal coin exchanges helps tailor practical recordkeeping steps for UAE holders.
Common seller profiles
Typical searchers include collectors thinning a collection, bullion investors rebalancing a portfolio, and occasional sellers needing short-term cash. Many investors prefer clear examples for different investment purposes.
What counts as a sale versus a swap or gift
A sale is a disposition for money or money’s worth. Swaps, trades, and gifts can still create documentation needs even when no cash changes hands. Keep dates and agreed price or fair market evidence.
Why intent and product type matter
Intent shapes documentation: regular trading looks different from one-off hobby selling. Sellers should record acquisition cost, holding time, and motive to reduce disputes and support bank or cross-border queries.
| Seller type | Typical objective | Evidence to keep |
|---|---|---|
| Collector | Rarity/long-term hold | Invoices, grading reports |
| Bullion investor | Market exposure | Purchase receipts, spot reference |
| Occasional seller | Cash flow | Payment proof, sale agreement |
For broader estate and collectibles context, see estate and collectibles guidance.
UAE Tax Snapshot for Individuals Selling Coins
Before listing items, UAE residents commonly run a short checklist to see if local rules or platform requirements apply.
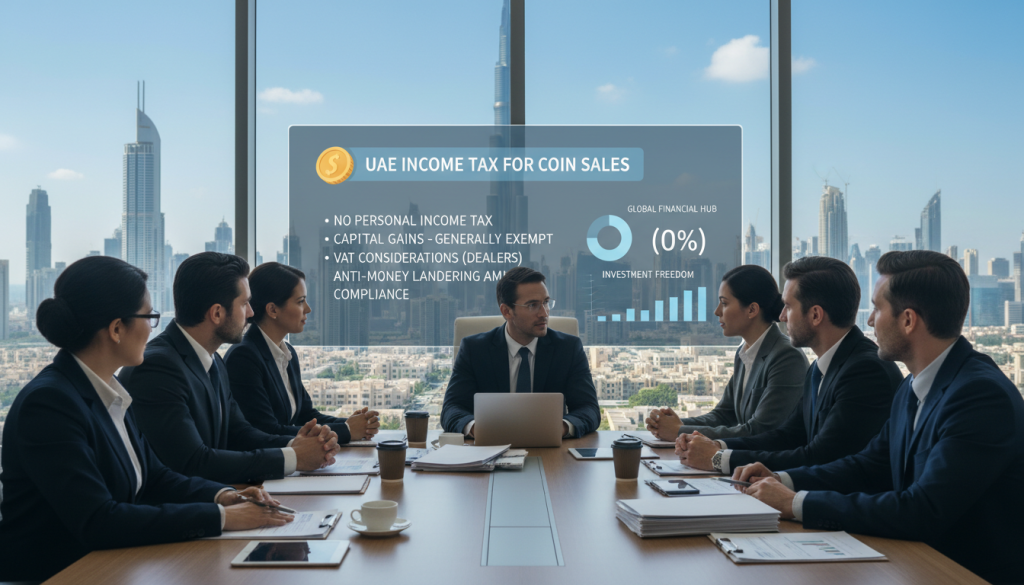
What residents typically check
First checks: is there personal income tax here, or do any platform or counterparty processes create reporting obligations? Many also confirm whether cross-border buyers trigger reporting or a foreign return.
Casual selling versus professional dealing
Behavior matters. Occasional selling of personal items usually needs less documentation. Frequent, advertised, or high-value activity can look like a business. That changes record expectations and potential liability.
- High frequency, large values, or dealer-like pricing increases scrutiny.
- Keep invoices, consistent pricing records, and fee proofs when activity rises.
- Even without local income tax, banks and platforms may request source-of-funds information.
| Scenario | When to worry | Recommended records |
|---|---|---|
| One-off sale | Low | Receipt, photos |
| Regular selling | Medium | Invoices, pricing logs |
| Dealer-style activity | High | Full bookkeeping, contracts, bank records |
Cross-border note: sellers with foreign ties should check other jurisdictions for capital or income tax rules before assuming no filing is needed. Investors who scale activity should seek professional advice to avoid creating an unintended trading footprint.
tax treatment private coin sales: What Usually Drives Tax Outcomes
What ultimately matters for cross-border compliance is the net gain you report—not the headline sale price. Regulators and banks look for the profit after costs, because that amount often determines reporting, disclosure, or foreign filing needs.
Profit vs. proceeds: why your gain (not the sale price) matters
Net gain is sale proceeds minus your cost basis and allowable fees. That number is the central analytic point in many capital frameworks—whether a country treats collectibles as capital assets or property.
Frequency and “trading behavior” as a risk flag
Repeated short holds, advertising, and inventory-style pricing raise red flags. Regulators and counterparties often treat such patterns as business activity rather than occasional disposals.
Asset classification and recordkeeping needs
Coins are commonly classified as property or collectibles in global models. That classification guides which records to keep: invoices, acquisition dates, and evidence of rarity or grading.
Holding period logic: short-term vs. long-term
Many systems compare holding time—under a year versus over a year—to decide rates or treatment. Recording acquisition and sale dates is simple but essential, especially for those with cross-border ties.
| Driver | What it shows | Documents to keep | Why it matters in UAE context |
|---|---|---|---|
| Net gain | Actual profit/loss amount | Purchase receipt, sale invoice, fees | Explains cash flows to banks and foreign authorities |
| Frequency | Whether activity looks like trading | Listing history, ads, sales calendar | May change classification to business activity |
| Holding period | Short-term vs long-term treatment | Acquisition date, sale date | Impacts comparative rates and cross-border filings |
Coins, Bullion, and Collectibles: How Product Type Impacts the Analysis
Different product types—sovereign-minted bullion, privately struck rounds, and numismatic rarities—drive distinct pricing and proof requirements. Sellers in the UAE should first identify whether an item trades on metal content or on collectible premium.
Bullion coins versus privately minted rounds
Sovereign-minted bullion often carries legal recognition and ready comparables. That supports liquidity and easier evidence of market price for banks and platforms.
Privately struck rounds tend to follow spot metal and need clear assay or provenance to support value. In some jurisdictions this difference even affects capital gains tax outcomes.
Numismatic and rare items
Rare pieces behave like collectibles: premiums widen, comparable sales vary, and graded condition can swing outcomes. Keep invoices, photos, and grading reports to justify a non‑metal premium.
Gold versus silver dynamics
Both metals can be bullion-driven, but silver often carries higher percentage premiums and wider dealer spreads. Gold usually shows tighter spreads and higher absolute value per unit.
- Buyer’s tip: decide if the item is metal‑value or rarity‑value before choosing a sales channel.
- Document provenance, weight, and grading to support declared gains and any local exemption queries.
Calculating Your Gain: Sale Price, Cost Basis, and Market Value
Calculating the gain starts with clear proof of what was paid and the fees tied to purchase.
Cost basis when you bought the item
Cost basis is the purchase price plus documented acquisition fees—broker commissions, platform charges, and insured shipping.
Keep receipts and transaction confirmations to show the original cost and any adjustments that raise that basis.
Inherited assets and fair market value
When there is no purchase invoice, the usual approach is to use the fair market value at the time of inheritance.
Support that value with dated appraisals or comparable sales from the same year to make the figure defensible.
When appraisals matter
Appraisals are vital for rare or thin-market items where online comparables vary widely.
Use graded reports or independent valuers to establish market value when the price is not obvious.
Worked example and evidence to keep
Example: Sale price $5,000 − basis $3,200 (purchase $3,000 + $200 fees) − platform commission $200 = net gain $600.
Save invoices, bank transfers, grading certificates, dated photos, and email negotiations. These support reported gains and answer bank or cross-border queries.
| Item | Line amount | Document to keep |
|---|---|---|
| Purchase price | $3,000 | Invoice, receipt |
| Acquisition fees | $200 | Broker fee records |
| Sale proceeds | $5,000 | Sale invoice, bank receipt |
| Platform commission | $200 | Platform statement |
| Net gain | $600 | Consolidated worksheet |
What Costs and Adjustments to Track Before You Sell
Count every fee and outlay up front. A short tally helps set a realistic target net gain and avoids surprises when reconciling bank receipts.
Transaction costs and dealer spreads
Dealers often buy below market and sell above it — the dealer spread can change the effective price you realize.
Include platform listing fees, payment processing charges, and commissions when estimating the net amount you will receive.
Grading, authentication, and restoration
Grading or authentication fees can raise saleability for rare pieces and may increase realized gains.
Restoration may boost value but can also harm collector confidence if done poorly. Keep before/after photos and all invoices.
Shipping, insurance, and storage
Small cash or card payments add up: insured shipping, secure storage, and handling should be recorded.
These out-of-pocket costs matter for disputes and for explaining net proceeds to banks or foreign reviewers.
- Estimate total frictional costs and subtract from your target net price.
- Decide channel: dealer offers speed; private buyers may pay higher premiums for rare gold items.
- Keep one folder per lot with receipts, certificates, and photos for neat reconciliation.
| Cost type | Example | Include in basis? | Document to keep |
|---|---|---|---|
| Dealer spread | Buy vs. sell gap | No—affects proceeds | Offer letters, invoices |
| Platform/commission | Marketplace fees, agent cut | Yes—commonly added to basis | Platform statements, receipts |
| Grading/authentication | Third-party grading | Yes—if it improves sale value | Grading certificate, invoice |
| Shipping & insurance | Insured courier charges | Yes—out-of-pocket expense | Courier receipt, tracking |
| Restoration/cleaning | Professional conservation | Case-by-case | Before/after photos, repair bills |
Practical note: apply global basis logic where applicable, keep records, and plan to explain net gains if reviewers ask about the transaction. Sellers in the UAE will benefit from this disciplined approach when moving high-value gold or bullion lots across borders.
Understanding Capital Gains Concepts (Even If the UAE Treatment Differs)
How an asset is used—long-term hold versus frequent flipping—often decides whether profits are viewed as capital gains or ordinary income in many countries.
Two common global models
Investment model: Gains from longer-held items are classed as capital gains and may get favourable rates.
Income model: Frequent dealing or short holds can be taxed as ordinary income, with different reporting rules.
Why collectibles sometimes face higher rates
Some jurisdictions impose a specific collectibles rate that is higher than standard long-term capital gains. The IRS, for example, may cap long-term collectibles gains at around 28% while short holds can be taxed at ordinary income rates within a year.
Practical implications for UAE sellers
Even where local obligations differ, international banks and foreign authorities expect clear dates and proof of basis. Keep receipts, appraisals, fee logs, and a concise asset description to support cross-border queries.
| Model | What it implies | Typical holding period | Docs to keep |
|---|---|---|---|
| Capital gains | Investment-focused profit | >1 year | Purchase invoice, sale record, fees |
| Ordinary income | Business-like trading | ≤1 year or frequent | Listing history, bank transfers, contracts |
| Collectibles rate | Higher capped rate for rarities | Varies by jurisdiction | Grading reports, comps, appraisals |
Losses, Break-Even Sales, and Down Markets
When prices fall, the difference between an unrealized decline and an actual loss hinges on the sale event.
Realized vs. unrealized declines
Realized losses occur only when an item is sold for less than its documented basis. Keep the sale invoice and bank receipt to prove the event.
Unrealized declines are paper changes in market value that do not count until a disposition happens. Do not treat a market dip as a loss for recordkeeping.
Break-even and documentation
Even a break-even sale needs paperwork. A clear basis, fee evidence, and a final invoice strengthen a “no gain” claim if reviewers ask.
Regimes that limit loss offsets
Some jurisdictions restrict claiming losses on personal-use collectibles or limit offsets against other income. This can affect capital gains or income return calculations—so classification matters.
- Define realized vs. unrealized: sale confirmation makes a loss real.
- Preserve dealer quotes, spot context, and listing history in down markets.
- Avoid retroactive reconstruction—record at the time of sale for stronger proofs.
| Item | When it’s a loss | Docs to keep | Typical impact |
|---|---|---|---|
| Realized loss | Sold below basis | Sale invoice, bank receipt, fees | May offset gains (subject to rules) |
| Unrealized decline | Price drop only | Spot snapshot, quotes | No effect until sale |
| Restricted loss | Collectible/personal-use class | Classification evidence, appraisal | Often limited on returns |
Practical note: consistent tracking helps decide whether to sell for liquidity or hold until spreads recover. Good records simplify any cross-border return questions and support prudent decisions in a weak market.
Private Sale Channels and Their Compliance Considerations in the UAE
Choosing the right sale channel shapes the paperwork, speed, and final amount you receive.
Selling to a dealer versus another buyer
Dealers often offer speed and clear, consistent paperwork — useful for quick liquidity or large gold lots.
Direct buyer sales can yield a better price but demand stronger records: signed receipts, messages, and proof of transfer.
- Dealers: faster closing, standard form invoices, lower negotiation risk.
- Buyer-to-buyer: higher price potential, greater documentation burden and potential liability.
Online marketplaces and cross-border buyers
Marketplaces increase the documentation bar. Keep screenshots, listing history, and platform fee statements to build an audit trail.
- Cross-border: save currency conversion records, shipping/export paperwork, and delivery confirmation.
- Platform transactions: retain identity checks, message threads, and escrow receipts where used.
Cash transactions: reduce disputes with simple protocols
Cash is common for small lot trades but raises verification needs for larger amounts. Use a written receipt and a count-and-confirm routine.
- Prefer bank transfer or escrow for high-value gold or coins.
- Maintain a single “sale packet”: invoice, payment proof, buyer communication log, and handover photos.
Good compliance hygiene protects against chargebacks, supports bank queries, and clarifies any tax or liability questions that arise after a sale.
Special Transaction Types: Gifts, Inheritance, and Non-Cash Trades
When ownership moves without cash, a brief written record can prevent big headaches for recipients and banks.
Gifting is a documentation event. Even with no payment, record the item, date, and an evidence-backed value so the recipient knows their future cost basis.
Inheritance and fair market value
For inherited property, many systems use market value at the date of transfer. Use a professional appraisal, a reputable dealer quote, or comparable auction results adjusted for grade and condition.
Swaps and non-cash trades
Swapping an asset for bullion or another asset is often treated as a disposition. Record both sides’ agreed values on the swap date to show any gain or loss later.
“A clear transfer memo reduces disputes and speeds cross-border reviews.”
- Keep a short transfer memo: date, parties, description, grade/cert number, agreed value, signatures.
- Take dated photos and keep dealer or auction comparables.
- For high-value gold lots, prefer written confirmation and receipts.
| Transaction type | What to record | Why it matters |
|---|---|---|
| Gift | Item description, agreed value, recipient name | Establishes recipient’s future basis |
| Inheritance | Appraisal or comps, date of transfer | Sets market value for later capital events |
| Swap | Both items’ values, signed swap memo | Shows disposition and any realized gains |
Crypto vs. Coins: Avoiding Category Errors When Thinking About Taxes
Different legal frameworks govern bytes and bullion; treating them the same invites mistakes.
Digital assets are often subject to bespoke rules: flat rates, withholding, and specific reporting forms. For example, India taxes crypto gains at a high flat rate and requires a small TDS on certain transfers. Swaps and gifting of tokens can also trigger reporting and unique filing forms.
By contrast, physical bullion and numismatic items are tangible property. That distinction matters because withholding-style mechanisms used for tokens do not automatically apply to a coin sale in the UAE. Assuming they do can produce wrong expectations about bank checks or required paperwork.
Practical guidance for UAE holders
- Label records clearly—separate crypto trade logs from bullion invoices and photos.
- Use neutral terms: “coin sale,” “bullion purchase,” “numismatic sale,” or “swap.”
- Keep acquisition dates, purchase currency, and proof of proceeds in a single folder for each lot.
| Asset class | Common rule | Reporting example |
|---|---|---|
| Digital asset | Withholding/flat rate | India: 30% flat, 1% TDS, specific forms |
| Physical bullion | Property rules, documentation | Invoices, appraisals, date-stamped proof |
| Numismatic | Premium-based valuation | Grading reports, sale invoice |
Documentation Checklist for Coin Investors Selling in the UAE
A compact, reliable record set makes cross-border reviews and bank queries far easier to resolve. The goal is a single file per lot that proves provenance, dates, and the net outcome.
What to keep
Core forms and receipts: purchase invoices, dealer receipts, bank transfer proof, and platform confirmations. Include grading certificates (PCGS/NGC), assay cards, serial numbers, and high-resolution photos of obverse/reverse and packaging.
Recording dates, amounts, and value
Use a consistent form for each item: description, acquisition date, sale date, sale price, basis, adjustments, and gain/loss. Record the market value evidence used — auction comps, dealer quotes, or appraisals — and note the valuation method in the file.
Communications, naming, and storage
Keep buyer messages, quotes, and agreement emails to validate price and timing. Use a clear naming form: YYYY-MM-DD_Asset_Grade_Amount. Store copies in cloud plus local encrypted backup.
| Asset | Qty | Cost basis | Sale price | Net gain/loss |
|---|---|---|---|---|
| Gold sovereign, 2020 MS70 | 1 | $1,200 | $1,500 | $280 |
| Silver round, BU | 10 | $220 | $250 | $20 |
Benefit: disciplined tracking improves pricing decisions, lowers fraud risk, and preserves the option to explain returns if residency or cross-border rules change.
Buyer’s Guide: Planning a Tax-Smart Coin Sale in the UAE
Deciding what to offer first—sovereign pieces, rounds, or bars—starts with who will buy and how quickly.
Choosing what to sell for liquidity and pricing
Sovereign gold coins tend to trade with easier recognition and tighter spreads. That helps when speed matters and when banks or foreign reviewers ask for standard comparables.
Rounds and bars suit metal-weight buyers who prioritise spot exposure. Graded numismatic items can command premiums when collector demand is strong.
Timing the sale
Gold price moves matter. Premiums expand in thin markets and contract in deep liquidity. Capture market value evidence: dealer quotes, bid/ask screenshots, and recent comparable trades.
Set a target window — a few days to a few weeks — and monitor spot and dealer spreads to maximise net proceeds.
When to consult an advisor
Seek professional advice for large holdings, frequent transactions that resemble trading, or when cross-border links exist. An adviser helps document classification, holding period, and any potential capital gains concerns.
Risk management and settlement
Authenticate items before listing: verify grading cert numbers and check common counterfeiting signs on popular gold coins. Use reputable counterparties and insist on escrow or insured transfer for high-value lots.
- Execution plan: choose channel, assemble docs, set price method, run net-proceeds math, complete the transfer, archive the file.
- Records to keep: invoices, delivery receipts, bid/ask snapshots, and authentication certificates.
| Choice | Best for | Docs to prepare |
|---|---|---|
| Sovereign gold coins | Liquidity & recognition | Invoice, grading/cert number, recent dealer quote |
| Rounds & bars | Metal-weight buyers | Weight assay, purchase receipt, spot snapshot |
| Numismatic pieces | Collectors, higher premiums | Grading report, comps, provenance |
Conclusion
A focused record and a matched channel make the difference for UAE sellers of gold and coins.
Document the purchase basis, dates, fees, and sale confirmations so the reported gain is clear. For inheritance, gifts, or swaps, add valuation evidence and a short transfer memo.
Choose a sales route that fits the lot: sovereign bullion for liquidity; rounds and bars for metal buyers; graded rarities for collectors who pay premiums. Monitor spreads and net profit, not just headline price.
Use global capital concepts—holding period, income vs. capital gain—as reference points to future‑proof files. For large amounts or complex residency links, consult an adviser and keep a clean, dated archive so any later query or return is straightforward.
FAQ
What does “private coin sales” mean in the UAE context?
Who is this buyer’s guide aimed at?
When is a transfer considered a sale rather than a gift, swap or trade?
How does coin type and intent affect how I should document a transaction?
Do UAE residents face income tax on private coin disposals?
When might coin selling be treated like a business rather than casual selling?
Why does profit matter more than the sale price?
How does frequency of sales affect scrutiny?
How should I classify coins for recordkeeping purposes?
Does holding period matter for coins in the UAE?
How do bullion coins differ from privately minted rounds for resale implications?
Why are numismatic coins treated differently?
How should I determine cost basis for a coin I bought previously?
What basis rules apply to inherited coins?
When are appraisals necessary?
Can you give a simple worked example of gain calculation?
FAQ
What does “private coin sales” mean in the UAE context?
The phrase refers to transfers of physical coins—bullion, rounds, or numismatic pieces—between non-professional parties, for example an individual seller and a private buyer. It excludes regulated dealer transactions or exchange-listed trades. Intent and context matter: casual disposals by a collector differ from activity that looks like regular commercial dealing.
Who is this buyer’s guide aimed at?
This guide targets collectors, occasional sellers, and individual investors in the United Arab Emirates who trade physical coins privately and want practical guidance on recordkeeping, valuation and how different transaction types can affect reporting and liability.
When is a transfer considered a sale rather than a gift, swap or trade?
A transfer is usually a sale when the seller receives cash or a cash-equivalent price. Swaps or coin-for-coin trades are treated as dispositions in many jurisdictions and should be documented as if sold at fair market value. Gifts require valuation evidence to establish the recipient’s future basis; documentation prevents disputes.
How does coin type and intent affect how I should document a transaction?
Legal tender bullion, privately minted rounds and numismatic coins carry different resale patterns and premiums. If you buy for investment versus collecting, keep purchase invoices, grading reports and notes on intent—these items help demonstrate whether activity was occasional or business-like, which can affect scrutiny.
Do UAE residents face income tax on private coin disposals?
The UAE does not levy personal income tax for most residents. However, certain transaction-based obligations, reporting requirements or business-designation rules can apply—especially if activity resembles trading or professional dealing. Keep robust records to show the sporadic nature of sales.
When might coin selling be treated like a business rather than casual selling?
Frequent transactions, marketing activity, purchasing for resale, or operating through platforms can signal professional dealing. If authorities view your activity as a commercial enterprise, you may face different regulatory or reporting obligations and should seek local advice.
Why does profit matter more than the sale price?
Financial outcome hinges on gain—sale proceeds minus cost basis and eligible expenses—not gross sales. Net gain determines economic benefit and any applicable reporting exposure. Accurate basis and expense tracking are essential to calculate the true profit.
How does frequency of sales affect scrutiny?
Repeated transactions suggest trading behavior. High frequency increases the risk of reclassification from occasional selling to a business activity, prompting closer examination of income streams and compliance requirements.
How should I classify coins for recordkeeping purposes?
Treat coins as tangible property: document acquisition date, purchase price, fees, grade or assay, and sale details. Use clear labels for bullion versus collectibles, since rarity and premiums affect valuation and evidence needs.
Does holding period matter for coins in the UAE?
The UAE does not follow the same short-term versus long-term capital gains frameworks used elsewhere, but holding period still matters for establishing intent and for valuation support—long-held items with documentary history face less challenge when sold infrequently.
How do bullion coins differ from privately minted rounds for resale implications?
Bullion coins often carry recognized legal-tender status and tighter market pricing; privately minted rounds trade more on dealer spreads and liquidity can vary. Both require invoices and weight/purity evidence to support valuations.
Why are numismatic coins treated differently?
Rare or collectible coins have premiums based on rarity, condition and provenance. Those premiums can complicate fair market value assessment and need corroborating sales comps, auction results or grading certificates.
How should I determine cost basis for a coin I bought previously?
Cost basis equals the purchase price plus eligible fees such as commissions, grading and authentication charges. Keep invoices and receipts to substantiate the basis if questioned later.
What basis rules apply to inherited coins?
For inherited items, value is generally established at the date of death using fair market value. Use comparable sales, auction records or professional appraisals to support the valuation applied when the estate transferred the asset.
When are appraisals necessary?
Obtain appraisals when market value is unclear—rare coins, unusual provenance, or low-liquidity items. A qualified numismatist or reputable auction house report strengthens documentation and substantiates declared proceeds or basis.
Can you give a simple worked example of gain calculation?
Example: sale price ,000 minus cost basis ,200 (purchase plus grading fee 0) and selling expenses 0 yields net gain
FAQ
What does “private coin sales” mean in the UAE context?
The phrase refers to transfers of physical coins—bullion, rounds, or numismatic pieces—between non-professional parties, for example an individual seller and a private buyer. It excludes regulated dealer transactions or exchange-listed trades. Intent and context matter: casual disposals by a collector differ from activity that looks like regular commercial dealing.
Who is this buyer’s guide aimed at?
This guide targets collectors, occasional sellers, and individual investors in the United Arab Emirates who trade physical coins privately and want practical guidance on recordkeeping, valuation and how different transaction types can affect reporting and liability.
When is a transfer considered a sale rather than a gift, swap or trade?
A transfer is usually a sale when the seller receives cash or a cash-equivalent price. Swaps or coin-for-coin trades are treated as dispositions in many jurisdictions and should be documented as if sold at fair market value. Gifts require valuation evidence to establish the recipient’s future basis; documentation prevents disputes.
How does coin type and intent affect how I should document a transaction?
Legal tender bullion, privately minted rounds and numismatic coins carry different resale patterns and premiums. If you buy for investment versus collecting, keep purchase invoices, grading reports and notes on intent—these items help demonstrate whether activity was occasional or business-like, which can affect scrutiny.
Do UAE residents face income tax on private coin disposals?
The UAE does not levy personal income tax for most residents. However, certain transaction-based obligations, reporting requirements or business-designation rules can apply—especially if activity resembles trading or professional dealing. Keep robust records to show the sporadic nature of sales.
When might coin selling be treated like a business rather than casual selling?
Frequent transactions, marketing activity, purchasing for resale, or operating through platforms can signal professional dealing. If authorities view your activity as a commercial enterprise, you may face different regulatory or reporting obligations and should seek local advice.
Why does profit matter more than the sale price?
Financial outcome hinges on gain—sale proceeds minus cost basis and eligible expenses—not gross sales. Net gain determines economic benefit and any applicable reporting exposure. Accurate basis and expense tracking are essential to calculate the true profit.
How does frequency of sales affect scrutiny?
Repeated transactions suggest trading behavior. High frequency increases the risk of reclassification from occasional selling to a business activity, prompting closer examination of income streams and compliance requirements.
How should I classify coins for recordkeeping purposes?
Treat coins as tangible property: document acquisition date, purchase price, fees, grade or assay, and sale details. Use clear labels for bullion versus collectibles, since rarity and premiums affect valuation and evidence needs.
Does holding period matter for coins in the UAE?
The UAE does not follow the same short-term versus long-term capital gains frameworks used elsewhere, but holding period still matters for establishing intent and for valuation support—long-held items with documentary history face less challenge when sold infrequently.
How do bullion coins differ from privately minted rounds for resale implications?
Bullion coins often carry recognized legal-tender status and tighter market pricing; privately minted rounds trade more on dealer spreads and liquidity can vary. Both require invoices and weight/purity evidence to support valuations.
Why are numismatic coins treated differently?
Rare or collectible coins have premiums based on rarity, condition and provenance. Those premiums can complicate fair market value assessment and need corroborating sales comps, auction results or grading certificates.
How should I determine cost basis for a coin I bought previously?
Cost basis equals the purchase price plus eligible fees such as commissions, grading and authentication charges. Keep invoices and receipts to substantiate the basis if questioned later.
What basis rules apply to inherited coins?
For inherited items, value is generally established at the date of death using fair market value. Use comparable sales, auction records or professional appraisals to support the valuation applied when the estate transferred the asset.
When are appraisals necessary?
Obtain appraisals when market value is unclear—rare coins, unusual provenance, or low-liquidity items. A qualified numismatist or reputable auction house report strengthens documentation and substantiates declared proceeds or basis.
Can you give a simple worked example of gain calculation?
Example: sale price $5,000 minus cost basis $3,200 (purchase plus grading fee $200) and selling expenses $100 yields net gain $1,700. Retain invoices, payment records and transfer correspondence as evidence.
Which costs can I track to reduce reported gain?
Track dealer spreads, platform fees, commissions, grading and authentication expenses, and direct out-of-pocket costs like shipping and insurance. Document payments and receipts to support adjustments to basis or sale proceeds.
Do restoration or grading costs affect basis?
Restoration, grading and authentication fees may increase basis when they materially enhance value or are necessary for sale. Keep invoices and a short note justifying how the expense affected the asset’s value.
How should I document shipping, insurance and storage expenses?
Keep receipts and bank or card statements showing the payment, carrier tracking, and insurance policies. These costs help demonstrate total out-of-pocket expenses related to the disposition.
What is the difference between capital gains and ordinary income models elsewhere?
Globally, capital gains tax applies to profits from asset disposals, often with distinct rates or holding-period rules. Ordinary income rules tax recurring business revenue at standard rates. While the UAE’s individual regime differs, these models help inform good recordkeeping.
Why do some countries tax collectibles at higher rates?
Collectibles often attract higher rates because premiums reflect rarity and speculative value. Higher rates discourage tax-driven painting of income and maintain consistency across asset classes—knowing this helps UAE sellers prepare documentation used in cross-border contexts.
How do I separate realized losses from unrealized value changes?
A realized loss occurs upon disposition for less than basis with supporting sale records. Unrealized changes—market fluctuations while holding—are not final until a sale. Keep dated valuations and sales evidence to prove realization events.
Are loss offsets for collectibles restricted in other regimes?
Yes. Some jurisdictions limit deductibility of losses on collectibles or restrict offsets to certain income types. UAE sellers with cross-border exposure should note foreign rules when filing abroad or dealing with nonresident buyers.
What documentation differs when selling to a dealer versus a private buyer?
Dealers usually provide purchase receipts and may offer consignment records; private buyers require clear invoices, proof of payment and signed transfer statements. Maintain both types of records to establish proceeds and chain of ownership.
How should I handle online marketplace or cross-border sales?
Maintain platform invoices, buyer communications, shipping records, and customs paperwork for cross-border transactions. These items form an audit trail and demonstrate arms-length pricing and transfer terms.
What precautions apply to cash sales?
For cash sales, obtain a signed receipt with buyer and seller details, price, date and coin identifiers. Use bank deposits or escrow where possible to reduce disputes and prove receipt of funds.
How are gifts of coins typically valued for documentation?
Value gifts at fair market value on the date of transfer using comparable sales or appraisal reports. Document the gift with a written declaration and recipient details to record the transaction for future basis questions.
How should inherited coins be valued and documented?
Use fair market value at the decedent’s date of death. Support valuation with auction results, appraisals, or dealer comps and keep estate transfer documents to substantiate the basis for subsequent sales.
Is swapping coin-for-coin treated as a disposition?
Conceptually yes—swaps are dispositions where each party must document the fair market value of what they received. Record the exchange date, valuations and any fees to show equivalent sale-like treatment.
How do digital asset tax models differ from tangible coin considerations?
Digital assets often have specific reporting regimes, automated tracking and withholding mechanisms in some countries. Physical coins lack those automated systems, so manual documentation and provenance proofs are critical when preparing records.
Do withholding-like rules apply to physical coin sales in the UAE?
Withholding regimes such as TDS in other countries generally do not apply automatically to private coin transfers in the UAE. Nevertheless, cross-border buyers or platforms may impose reporting or withholding—maintain clear invoices and proof of residency when relevant.
What documents should coin investors keep before selling?
Retain purchase invoices, grading certificates, assay cards, photos, correspondence with buyers or dealers, shipping receipts, and payment records. These items form the primary evidence for basis and proceeds calculations.
How should I record dates, amounts and market value at sale time?
Log acquisition and disposition dates, exact amounts paid and received, fees, and a short note on how market value was determined (auction comps, dealer quotes, or appraisals). Time-stamped screenshots of listings or exchange rates help support valuations.
Is there a simple tracking template I can use?
A minimal table should include: asset description, acquisition date, purchase price, fees, sale date, sale proceeds, selling fees, and net gain or loss. Keep backups of invoices linked to each entry for audit resilience.
Should I choose coins, rounds or bars for better liquidity?
Liquidity varies: widely recognized bullion coins (e.g., American Gold Eagle, Canadian Maple Leaf) often sell more easily and with tighter spreads than privately minted rounds. Bars can offer lower premiums but require assay proof. Consider market demand and resale channels.
How does timing affect sale outcomes?
Price volatility, seasonal demand and auction timing influence realized proceeds. Selling during strong markets or when comparable sales exist yields cleaner valuation evidence. Keep market snapshots to demonstrate timing rationale.
When should I consult a tax advisor or legal counsel?
Seek advice for high-value collections, frequent transactions, cross-border buyers, estate planning, or when uncertain about business classification. Local UAE advisors and international tax specialists can clarify regulatory and reporting risks.
What risk management steps reduce fraud and counterfeiting exposure?
Use reputable graders (NGC, PCGS), authenticated dealers, and escrow services for high-value trades. Retain assay reports, high-resolution photos and provenance records. Verify buyer credentials and prefer traceable payment methods.
,700. Retain invoices, payment records and transfer correspondence as evidence.
Which costs can I track to reduce reported gain?
Track dealer spreads, platform fees, commissions, grading and authentication expenses, and direct out-of-pocket costs like shipping and insurance. Document payments and receipts to support adjustments to basis or sale proceeds.
Do restoration or grading costs affect basis?
Restoration, grading and authentication fees may increase basis when they materially enhance value or are necessary for sale. Keep invoices and a short note justifying how the expense affected the asset’s value.
How should I document shipping, insurance and storage expenses?
Keep receipts and bank or card statements showing the payment, carrier tracking, and insurance policies. These costs help demonstrate total out-of-pocket expenses related to the disposition.
What is the difference between capital gains and ordinary income models elsewhere?
Globally, capital gains tax applies to profits from asset disposals, often with distinct rates or holding-period rules. Ordinary income rules tax recurring business revenue at standard rates. While the UAE’s individual regime differs, these models help inform good recordkeeping.
Why do some countries tax collectibles at higher rates?
Collectibles often attract higher rates because premiums reflect rarity and speculative value. Higher rates discourage tax-driven painting of income and maintain consistency across asset classes—knowing this helps UAE sellers prepare documentation used in cross-border contexts.
How do I separate realized losses from unrealized value changes?
A realized loss occurs upon disposition for less than basis with supporting sale records. Unrealized changes—market fluctuations while holding—are not final until a sale. Keep dated valuations and sales evidence to prove realization events.
Are loss offsets for collectibles restricted in other regimes?
Yes. Some jurisdictions limit deductibility of losses on collectibles or restrict offsets to certain income types. UAE sellers with cross-border exposure should note foreign rules when filing abroad or dealing with nonresident buyers.
What documentation differs when selling to a dealer versus a private buyer?
Dealers usually provide purchase receipts and may offer consignment records; private buyers require clear invoices, proof of payment and signed transfer statements. Maintain both types of records to establish proceeds and chain of ownership.
How should I handle online marketplace or cross-border sales?
Maintain platform invoices, buyer communications, shipping records, and customs paperwork for cross-border transactions. These items form an audit trail and demonstrate arms-length pricing and transfer terms.
What precautions apply to cash sales?
For cash sales, obtain a signed receipt with buyer and seller details, price, date and coin identifiers. Use bank deposits or escrow where possible to reduce disputes and prove receipt of funds.
How are gifts of coins typically valued for documentation?
Value gifts at fair market value on the date of transfer using comparable sales or appraisal reports. Document the gift with a written declaration and recipient details to record the transaction for future basis questions.
How should inherited coins be valued and documented?
Use fair market value at the decedent’s date of death. Support valuation with auction results, appraisals, or dealer comps and keep estate transfer documents to substantiate the basis for subsequent sales.
Is swapping coin-for-coin treated as a disposition?
Conceptually yes—swaps are dispositions where each party must document the fair market value of what they received. Record the exchange date, valuations and any fees to show equivalent sale-like treatment.
How do digital asset tax models differ from tangible coin considerations?
Digital assets often have specific reporting regimes, automated tracking and withholding mechanisms in some countries. Physical coins lack those automated systems, so manual documentation and provenance proofs are critical when preparing records.
Do withholding-like rules apply to physical coin sales in the UAE?
Withholding regimes such as TDS in other countries generally do not apply automatically to private coin transfers in the UAE. Nevertheless, cross-border buyers or platforms may impose reporting or withholding—maintain clear invoices and proof of residency when relevant.
What documents should coin investors keep before selling?
Retain purchase invoices, grading certificates, assay cards, photos, correspondence with buyers or dealers, shipping receipts, and payment records. These items form the primary evidence for basis and proceeds calculations.
How should I record dates, amounts and market value at sale time?
Log acquisition and disposition dates, exact amounts paid and received, fees, and a short note on how market value was determined (auction comps, dealer quotes, or appraisals). Time-stamped screenshots of listings or exchange rates help support valuations.
Is there a simple tracking template I can use?
A minimal table should include: asset description, acquisition date, purchase price, fees, sale date, sale proceeds, selling fees, and net gain or loss. Keep backups of invoices linked to each entry for audit resilience.
Should I choose coins, rounds or bars for better liquidity?
Liquidity varies: widely recognized bullion coins (e.g., American Gold Eagle, Canadian Maple Leaf) often sell more easily and with tighter spreads than privately minted rounds. Bars can offer lower premiums but require assay proof. Consider market demand and resale channels.
How does timing affect sale outcomes?
Price volatility, seasonal demand and auction timing influence realized proceeds. Selling during strong markets or when comparable sales exist yields cleaner valuation evidence. Keep market snapshots to demonstrate timing rationale.
When should I consult a tax advisor or legal counsel?
Seek advice for high-value collections, frequent transactions, cross-border buyers, estate planning, or when uncertain about business classification. Local UAE advisors and international tax specialists can clarify regulatory and reporting risks.
What risk management steps reduce fraud and counterfeiting exposure?
Use reputable graders (NGC, PCGS), authenticated dealers, and escrow services for high-value trades. Retain assay reports, high-resolution photos and provenance records. Verify buyer credentials and prefer traceable payment methods.


