The Risk of Chargeback Methods: Cryptocurrency Payment Risks Explained

Surprising fact: global data shows that payment reversals cost merchants billions each year, and many stem from disputes that begin long after delivery.
This short guide explains the landscape for modern merchants, with a lens on crypto-adjacent flows where “irreversible” payments are not always dispute-proof.
Readers in the UAE should note common scenarios: cross-border sales, digital services, and multi-currency settlements can raise disputes and add operational strain.
The article will define how a chargeback works, where disputes come from, and why cryptocurrency can add friction to resolution paths. It will also cover practical prevention: reduce merchant errors, block fraud early, and counter friendly fraud with clearer evidence and support.
Why this matters commercially: a reversed transaction is more than a lost sale—it can trigger fees, penalties, and extra scrutiny from payment processors, harming cash flow and reputation.
Key Takeaways
- This guide outlines the mechanics behind chargebacks and typical dispute sources.
- UAE businesses face added complexity from cross-border and multi-currency transactions.
- Cryptocurrency can complicate dispute paths even when funds seem final.
- Prevention focuses on fewer merchant errors, early fraud screening, and better evidence.
- Later sections act as a checklist for checkout, fulfillment, fraud tools, and responses.
Why chargebacks are rising and why businesses feel it now
Recent years show a steady rise in customer disputes, and that increase is hitting merchants where it counts: cash flow and operations. Chargebacks have grown roughly 20% per year, which means many more incoming investigations and more funds put on hold during reviews.
The operational effect is simple: every disputed payment adds work. Teams must collect evidence, reply to issuing banks, and track outcomes. When funds are pulled, working capital tightens and short-term revenue can drop.
Chargebacks also bring direct costs. Merchants face non-refundable fees, penalties, and higher processing charges if disputes accumulate. That raises long-term merchant profile scores and can limit payment options for some businesses.
Globally, the projected number—337 million chargebacks by 2026—means more background noise for payment teams. Sectors like eCommerce, subscriptions, travel, and digital goods see more friction because card-not-present sales are common.
For UAE firms, the message is practical: prevention and swift response reduce direct losses and the hidden costs of handling disputes at scale.
What a chargeback is and how the dispute process works
A transaction reversal starts with a customer complaint and moves through banks and networks for review. Clear definitions help teams act fast and collect the right information.
Definitions: A refund is merchant-initiated and returns funds directly to the customer. A dispute is a cardholder claim raised with their issuer. A chargeback process is the issuer-driven reversal that can remove funds from a merchant account.
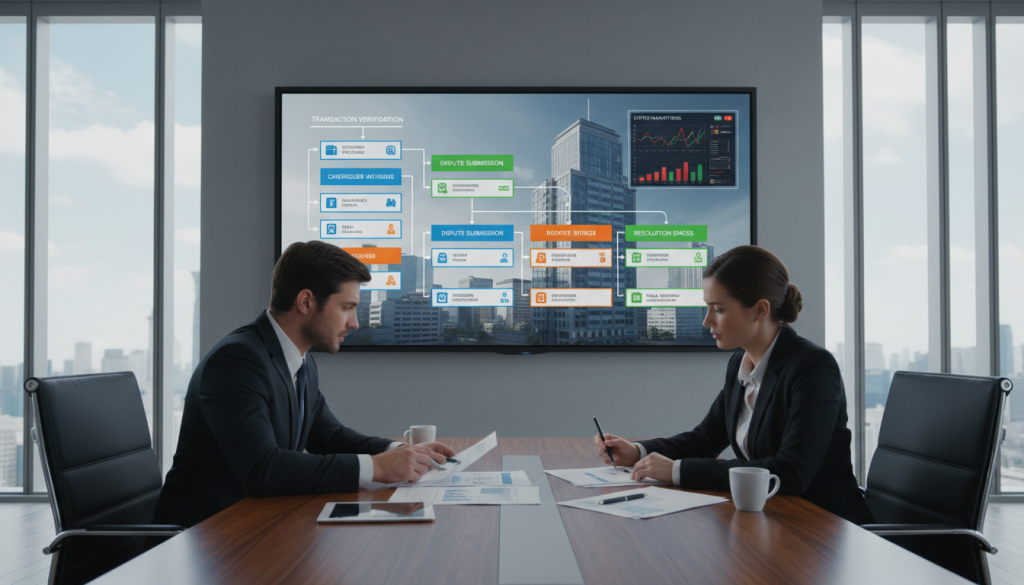
How the steps typically play out
- Notification: the merchant receives a case alert from the processor.
- Reason code: the issuer assigns a code that explains the claim.
- Evidence collection: merchant gathers receipts, tracking, and messages.
- Representment: merchant submits proof to contest the reversal.
- Escalation: networks may arbitrate if outcomes differ.
Common time windows and fast action
Submission windows are short—often 20–30 days—so meeting deadlines matters. Missing a deadline can lead to automatic loss even when evidence exists.
- Set alerts for new cases and deadlines.
- Centralize ownership so one team sends complete packets.
- Pre-build templates with order, delivery, and communication details.
Note: Even in crypto-adjacent sales, issuers use standard bank rules and proof to decide outcomes. Prepare traditional evidence early to improve results.
Where chargebacks come from in practice
Three-source model: most disputes fall into one of three categories — merchant error, criminal fraud, or first-party abuse — and each requires a different operational fix.
Merchant error chargebacks
These arise from billing mistakes, duplicate invoices, incorrect amounts, or late shipments. A clear invoice, correct SKU mapping, and timely tracking reduce these cases.
Criminal fraud and unauthorized transactions
Stolen credentials, account takeovers, and stolen cards create disputes where the cardholder is treated as the victim. Use authentication tools and velocity checks to catch fraudulent transactions early.
Friendly fraud and first-party abuse
Here, a legitimate purchase is disputed by the buyer or a household member due to confusion, remorse, or deliberate abuse. Detailed receipts, clear delivery notes, and documented consent help deter such claims.
Why classification matters: mislabeling a friendly fraud claim as criminal can add unnecessary friction, while treating theft as a service issue amplifies losses. Prevention differs: fix internal processes, deploy anti-fraud controls, and keep clearer evidence to discourage first-party disputes.
Risk of chargeback methods in crypto transactions
Crypto payments can feel final, yet the bank or card path that funded them may still trigger a later reversal.
Why on-chain finality does not end disputes
A common misconception: a token transfer cannot be reversed. That is true on-chain, but the customer’s original fiat funding—credit card or bank transfer—can be disputed upstream.
Card-not-present patterns that cause headaches
One familiar flow: a buyer uses a card to purchase crypto, then pays a merchant with that crypto. If the card holder later disputes the card charge, the merchant faces indirect loss and extra work.
Price swings and refund clarity
Volatility makes disputes emotional. Merchants should state whether refunds use fiat value, crypto units, or a fixed conversion time to avoid confusion.
Digital goods and instant delivery
Instant access to intangible goods invites friendly fraud. Clear delivery logs, strong checkout disclosures, and identity checks reduce abuse and protect outcomes.
| Issue | Why it happens | Practical fix |
|---|---|---|
| Upstream reversal | Funding dispute on a card or bank leg | Document funding, timestamps, and conversion rates |
| Card-not-present fraud | Remote purchases, VPNs, cross-border addresses | Stronger authentication and address verification |
| Price dispute | Crypto value shifts between sale and complaint | Clear refund policy with timestamped conversion |
For deeper tactics on crypto-related reversals, see cryptocurrency chargebacks for practical guidance and templates.
Merchant error triggers that quietly create chargebacks
Simple checkout glitches—refreshes, timeouts, or misapplied taxes—regularly lead to formal consumer complaints.
Duplicate charges and incorrect amounts
Duplicate billing often happens when a buyer refreshes a page, retries after an error, or faces a gateway timeout that still captures funds.
Incorrect totals arise from currency conversion slips, tax or shipping miscalculations, and manual invoice mistakes. These errors can prompt a credit dispute or a formal case that drains resources.
Noncompliance and authorization failures
When required card authorization or network rules are skipped, issuers may rule for the customer automatically. That makes routine verification steps essential.
Mismatch between listings and delivered product
Low-quality images or vague product descriptions cause expectation gaps. High-ticket items are scrutinized more closely and generate more disputes.
- Prevention: reconciliation checks and idempotency controls to stop duplicates.
- Set clear descriptor text on statements and QA product descriptions and images.
- Keep order details and billing information accurate for fast resolution.
Even with crypto-settled sales, customers judge transactions like standard eCommerce. Clear information and swift prevention help businesses reduce disputes and save time.
Fraud chargebacks and fraudulent transactions you need to spot early
Spotting fraudulent transactions early saves time and protects merchant accounts. Criminal fraud—stolen cards, counterfeit cards, and account takeover—creates the toughest disputes for merchants and issuing banks. Early detection lowers operational load and improves chances when contesting cases.
Stolen, counterfeit, and account-takeover patterns
Typical signs include mismatched identity details, rushed high-value purchases, and repeated declines followed by sudden approval. Fraudsters often change shipping or device behavior right before checkout.
Account takeover uses valid credentials, so login alone is not proof of customer intent. Strong authentication and session validation are essential.
IP, geolocation anomalies and velocity signals
IP and geolocation anomalies are clear flags, but not definitive—in the UAE, travelers and VPNs can create false positives. Use them as triggers for extra checks rather than automatic blocks.
Velocity controls should watch multiple transactions in short windows, many cards per account, or repeated attempts from one device fingerprint. These patterns often precede fraud chargebacks.
Evidence-grade logging and dynamic friction
Store authorization results, AVS/CVV outcomes, device signals, timestamps, and customer messages. Quality data builds defensible cases when a bank treats the cardholder as the victim.
- Transaction monitoring and risk scoring for live decisions.
- IP/geolocation checks and manual review for flagged orders.
- Apply heavier verification only on high-risk activity—dynamic friction preserves conversions.
Friendly fraud and how it shows up in crypto-adjacent commerce
Friendly fraud shows up in subtle ways across crypto-linked sales, often starting with simple buyer confusion. Merchants in the UAE face common patterns: remorse after a volatile trade, shared household payments, and disputes about instant digital delivery.
Buyer remorse and disputed purchases
Volatility in crypto can make a recent purchase feel wrong to a customer. That regret sometimes becomes a formal dispute rather than a support message.
Clear post-purchase emails and a short cooling-off window help turn complaints into refunds, not formal cases.
“I didn’t authorize it” household claims
Shared devices and saved payment details create plausible deniability. Customers living together may deny a purchase when they simply forgot or misunderstood who paid.
Checkout confirmations, one-click PINs, and visible account names reduce these claims.
“Item not received” and digital goods
Instant downloads, license keys, or account credits require delivery logs. Timestamps, IP data, and access records form strong evidence against incorrect non-receipt claims.
- Prevention: plain-language terms, clear return policies, and proactive renewal notices.
- Representment depends on documentation: acceptance logs, timestamps, IP/device evidence, and follow-up emails.
Fraud prevention stack that reduces chargebacks without killing conversions
A layered fraud prevention approach protects merchants while keeping checkout fast for genuine buyers. No single control stops every attack; combining checks creates a practical defense that lowers disputes and saves revenue.
3D Secure, two-factor, and biometric checks
3D Secure supplies issuer-backed authentication and can shift liability for many card-not-present transactions. Two-factor and biometric checks on wallets and accounts reduce account takeover and reinforce customer intent.
AVS, CVV, scoring, and manual review
Address Verification Service and CVV mismatches are high-signal items for scoring engines. Use real-time risk scoring and transaction limits to step up verification for unusual orders.
- Cap exposure on new accounts and apply manual review to high-value transactions.
- Run A/B tests and dynamic friction to protect conversion rates in the UAE and cross-border flows.
- Log payment and device data to build evidence for disputes and audits.
Infrastructure hygiene
Maintain secure gateways, least-privilege access, detailed logs, and PCI-DSS alignment. These practices reduce breach impact and prevent large waves of fraudulent activity.
Checkout clarity that helps prevent chargebacks before they start
Clear checkout pages cut confusion—when buyers see all costs up front they are far less likely to escalate a payment dispute. This improves conversion and gives a business stronger evidence if a customer later questions a payment.
Transparent pricing, taxes, shipping fees, and delivery timelines
Show totals before confirmation: include the final price, taxes, shipping, and any processing fees so customers know exactly what they will pay.
Mention expected delivery windows and clear shipping options to set realistic expectations for UAE buyers.
Detailed receipts and invoices that help customers remember purchases
Send line-item receipts with order numbers, payment information, and support contact details. Good documentation helps a customer self-verify charges and reduces formal disputes.
Clear Terms of Service acceptance and prominent disclaimers
Require an unchecked checkbox for Terms acceptance and store timestamped logs. Place visible disclaimers for cancellations, digital delivery, refund method, and renewals at checkout and in confirmation emails.
- Descriptor clarity: ensure the business name appears recognizably on billing statements to cut “I don’t recognize this charge” cases.
- Post-purchase information: include conversion timestamps, wallet addresses, and exchange rates for crypto-linked sales to prevent confusion.
- Evidence advantage: customers who find clear invoices and support routes rarely need to file formal complaints, which helps prevent chargebacks.
| Item | Why it matters | What to show |
|---|---|---|
| Pricing transparency | Reduces surprise and abandoned carts | Total price, taxes, shipping, fees |
| Receipt detail | Helps a customer recognize a purchase | Order number, line items, contact info |
| Statement descriptor | Prevents “unrecognized” billing disputes | Clear business name and short descriptor |
| Crypto conversion info | Clarifies value at time of sale | Rate, timestamp, wallet reference |
Fulfillment, shipping, and proof that win disputes
Every shipping event is an opportunity to create defensible data tied to an order. Treat fulfillment as evidence creation: each step should produce a verifiable record that stands up to issuer scrutiny.
Tracking numbers and delivery confirmation
Provide tracking by default and push real-time updates to customers. Carrier scans, timestamps, and delivery status form clear product delivery evidence.
Delivery confirmation lowers customer anxiety and reduces disputes by showing objective proof when a buyer questions receipt.
Organized records and signature policy
Link order ID, tracking, address, communications, and timestamps in one place. Centralized logs make evidence packets fast to assemble when deadlines are short.
Require signature on delivery for high-value goods. Signatures deter opportunistic claims and strengthen representment when contesting a chargeback.
- Store carrier scans and delivery notes alongside order details.
- Document customs, handoffs, and address formatting for UAE cross-border sales.
- Use proof-of-delivery logs to materially improve outcomes in disputes.
Customer service systems that defuse disputes fast
Accessible help channels steer frustrated customers toward resolution instead of filing a bank claim. Many formal disputes begin as unanswered tickets, so clear contact paths and fast responses are a direct prevention lever.
Contact details on every page and realistic support hours
Show email, phone, and a support form on desktop and mobile. Place contact info in the footer and checkout so customers can reach help at once.
Publish operating hours with UAE time zone clarity. Transparency sets expectation and reduces friction for international customers.
Response speed targets and escalation paths
Set clear targets: triage payment issues within minutes and shipping queries within hours. Fast replies stop many cases before they escalate.
- Allow agents authority to refund or adjust billing quickly.
- Define escalation steps so complex cases reach senior staff fast.
Blended support: chatbots plus human agents
Use chatbots for order status, tracking links, and FAQs. Route billing, cancellations, and identity-sensitive queries to trained humans.
Track ticket categories that correlate with disputes—“where is my order,” “renewal,” and “refund status”—to fix root causes and improve solutions over time.
| Issue | Target response | Action |
|---|---|---|
| Payment alert | Within 15 minutes | Triage and offer interim solution |
| Delivery query | Within 4 hours | Provide tracking and ETA |
| Refund request | 24 hours | Authorize or escalate |
Chargeback process playbook for crypto-focused businesses
A practical playbook helps teams sort disputes fast and decide when to escalate or stand down.
Reading reason codes and triage
Map reason codes into four buckets: fraud, authorization, consumer dispute, and processing error. Prioritize fraud and authorization cases where authentication logs or bank data indicate a clear fault.
Deciding when representment is worth it
Use a simple formula: expected recovery value minus labor cost and the likelihood of win. If recovery is low or evidence is weak, consider refund or a conciliatory solution to preserve the account relationship.
Evidence checklist
- Standard: order confirmation, AVS/CVV, 3DS logs, delivery proof, receipts.
- Crypto-specific: wallet address, transaction hash, timestamp, and exported session logs showing customer actions.
Tracking, ratios, and escalation
Set SLAs to assemble evidence within days; issuer windows are commonly 20–30 days. Monitor win rate, root causes, and your chargebacks ratio to avoid higher fees, holds, or account limits.
When to automate or hire experts
Use automation and dispute resolution programs when volume grows or staff is constrained. Engage specialists for complex fraud patterns, high-value disputes, or repeated reason-code losses.
| Metric | Target | Action |
|---|---|---|
| Win rate | >60% | Improve evidence & workflows |
| Response SLA | Centralize packet assembly | |
| Chargebacks ratio | Apply prevention & escalation |
Conclusion
A pragmatic closing view: systematic controls and clear records turn dispute events into solvable incidents, not crises.
Address merchant error, criminal fraud, and friendly abuse together to cut chargebacks and protect cash flow. For crypto-linked sales remember that on-chain finality does not remove upstream payment exposures when funding or delivery questions reach issuing banks.
Prioritize checkout clarity, layered fraud checks, and fulfillment logs that serve as fast, dispute-ready evidence. Run a monthly review of dispute data, refresh rules from new patterns, and train support teams on quick de-escalation steps.
Long-term gains are practical: fewer reversals improve margin, steady working capital, and better processor standing in UAE and cross-border markets. Treat this as continuous improvement and measure progress by win rate and chargebacks ratio—then iterate.
See our privacy policy for data handling details.